Florida Hometown Heroes Program 2026: Complete Guide to Down Payment Assistance for Frontline Workers
If you work as a nurse, teacher, firefighter, police officer, or in another frontline role in Florida, the state wants to help you buy your first home. The Florida Hometown Heroes Housing Program provides eligible frontline workers with substantial down payment and closing cost assistance, a competitive fixed mortgage rate, and a waived origination fee that can save thousands at closing.
After helping numerous Palm Beach County teachers, nurses, and first responders navigate this program, I’ve put together this complete guide covering exactly who qualifies, how much assistance you can get, and what the process actually looks like in 2026.
What Is the Florida Hometown Heroes Program?
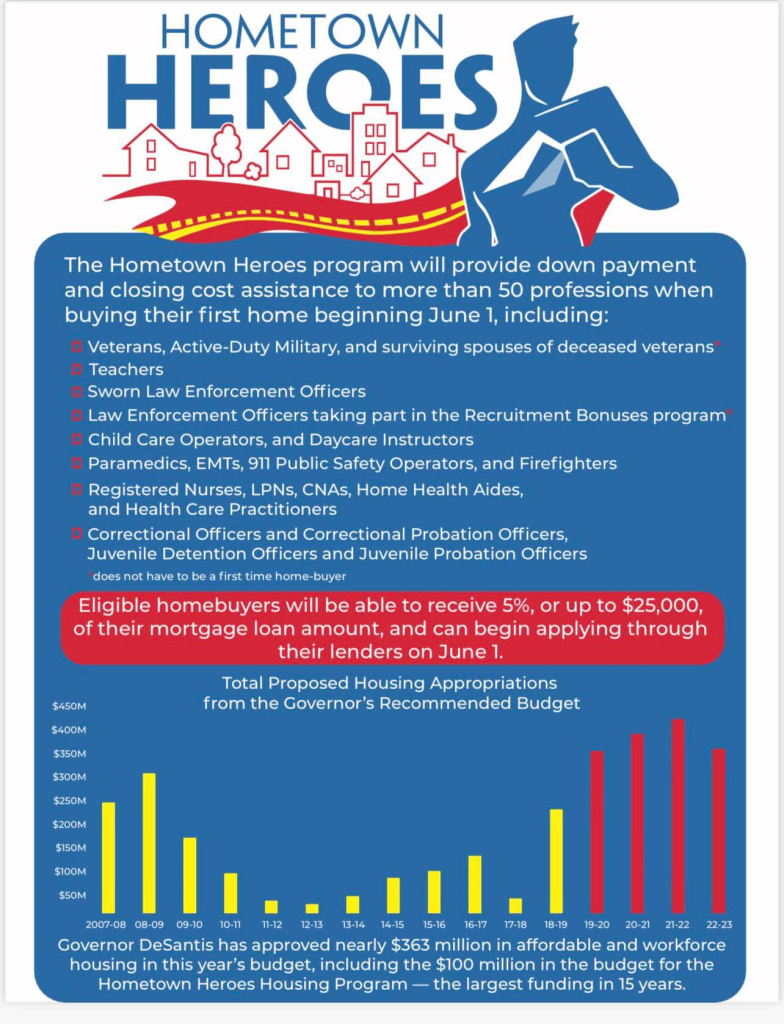
The Hometown Heroes Program helps Florida’s frontline workers buy their first home, including healthcare staff, K-12 school employees, first responders, law enforcement, court and childcare workers, and military members and veterans.
In exchange for the work these professionals do for their communities, the state offers a competitive 30-year fixed mortgage rate plus down payment and closing cost assistance, and waives the standard 1% origination fee, saving borrowers thousands more at closing.
This isn’t a niche program with a handful of qualifying jobs. It covers a wide swath of Florida’s essential workforce, and understanding whether you qualify often comes down to details many applicants overlook.
How Much Down Payment Assistance Can You Get?
The program provides 5% of your total loan amount in down payment and closing cost assistance, capped at $35,000, with a minimum of $10,000. For example, borrowers with a loan amount of $200,000 or less receive an automatic $10,000 in assistance.
Assistance Examples:
- $200,000 loan: $10,000 assistance (minimum guaranteed)
- $300,000 loan: $15,000 assistance
- $400,000 loan: $20,000 assistance
- $500,000 loan: $25,000 assistance
- $700,000+ loan: $35,000 assistance (maximum cap)
How the Second Mortgage Works
This assistance comes in the form of a 0%, non-amortizing, 30-year, repayable second mortgage. In plain terms:
- No interest accrues on this loan
- No monthly payments are required
- Repayment is deferred until you sell, transfer the property, pay off your first mortgage, refinance, or stop occupying the home as your primary residence
Once one of those triggering events occurs, the Hometown Heroes second mortgage becomes payable in full. It’s important to understand that this is a loan, not a grant.
There’s no cost to apply and no prepayment penalty, but the full amount you receive must eventually be repaid.
Who Qualifies? Eligibility Is About Your Employer, Not Your Title
One of the most misunderstood aspects of this program is eligibility.
Whether you qualify comes down to who employs you and where you physically work, not your specific job title.
A cafeteria worker or janitor employed at a hospital or K-12 school qualifies for the program, while a fully remote employee does not.
This distinction trips up a lot of applicants who assume their profession alone determines eligibility.
Core Eligibility Requirements
Primary Residence Requirement
The property you’re purchasing must become your primary residence, and you must be a Florida resident with the intent to occupy the property within 60 days of closing.
Florida-Based Employer
You must currently work full-time for an eligible Florida-based employer with a physical, brick-and-mortar location where you work from or report to. Remote and work-from-home employees are not eligible.
Hybrid employees qualify only if they’re on-site at least three days per week.
Veterans with a valid DD-214 don’t need to work in an eligible-type occupation, but they must still be employed full-time by a Florida-based employer. Only one occupying borrower needs to satisfy this employer requirement. Note that offer letters aren’t accepted—your employment must already be current and active.
First-Time Homebuyer Status
Occupying borrowers must not have had an ownership interest in their primary residence within the last three years, unless purchasing in a Federally Designated Targeted Area or qualifying under the Veteran’s Exemption.
Income Limits
Your household income must fall under the maximum limit for your county. This is where the two program versions differ significantly (explained below).
Homebuyer Education
The primary borrower must complete an approved pre-purchase homebuyer education course, either in-person or online. Certificates remain valid for two years from completion.
Veterans and active-duty military are exempt from this requirement unless they’re using a conventional HFA Preferred or HFA Advantage loan. Co-signers are not required to complete the course.
TBA vs. Bond: Understanding the Two Program Versions
The Hometown Heroes Program comes in two versions, and which one applies to you significantly affects both your income calculation and your loan options.
TBA Version
TBA counts only the income of the borrowers actually on the loan. This version offers FHA, USDA-RD, VA, and Freddie Mac (HFA Advantage) loan options.
Bond Version
Bond counts the income of everyone in the household aged 18 and older, including a spouse who isn’t on the loan. New for 2026, Fannie Mae (HFA Preferred) conventional loans are available only through the Bond version.
Because TBA only considers income from borrowers actually on the loan, it can be advantageous for households where a non-borrowing spouse or adult child earns significant income that would otherwise push the household over Bond’s income limit.
Your loan specialist will match you with whichever version fits your specific financial situation better.
Loan Terms and Requirements
Understanding the underlying loan terms helps you know what to expect throughout the process.
Credit Score Requirements
- Minimum FICO score: 640 for all loan types
- Manufactured housing and manual underwrites require a minimum of 660
- DU blended FICO scores are not permitted
Debt-to-Income (DTI) Ratios
- Maximum 50% DTI with automated underwriting system (AUS) approval
- Maximum 43% DTI with manual underwrites
- Maximum 45% DTI for manufactured housing
Mortgage Insurance
The first mortgage offers reduced mortgage insurance premiums for borrowers with income at or below 80% of Area Median Income (AMI). Borrowers with income above 80% AMI pay standard mortgage insurance rates.
Eligible Property Types
- Attached or detached 1-unit dwellings, including townhomes
- 2-4 unit properties, provided they’re at least 5 years old and the borrower occupies one unit as their primary residence
- Condos, with single-unit approval permitted for FHA loans
- Manufactured/modular housing built in 1994 or newer
Loan Purpose Restrictions
This program is for purchases only—refinances are not eligible. Assumptions are permitted only on government (GOVT) loans by a qualified borrower who satisfies first-time homebuyer requirements, income limits, and purchase price limits at the time of assumption.
Construction-to-permanent loans are not permitted under this program.
Prepayment is allowed at any time without penalty, on both the first mortgage and eventual repayment of the second mortgage assistance.
One-Time Program Participation
It’s important to know upfront that all borrowers are restricted to one-time participation in Florida Housing’s Homebuyer Loan Programs. This restriction includes all first and second mortgage programs offered through Florida Housing, not just Hometown Heroes specifically.
If you’ve previously used a Florida Housing program, you likely won’t be eligible to use this assistance again on a future purchase.
Additionally, Florida Housing’s down payment assistance cannot be combined with another Florida Housing DPA program. You’ll need to choose the program that best fits your situation, since stacking isn’t an option.
Documentation You’ll Need to Confirm Employment
Because eligibility hinges on your employer and work location, be prepared to provide solid documentation:
For Standard Employees
A copy of a Verification of Employment (VOE) confirming you work from a Florida location, or a letter from your employer confirming the same, is required. Paystubs confirming 40 hours weekly are acceptable, but if your paystubs don’t clearly reflect full-time hours, a written or verbal VOE or an employer letter verifying full-time status will be required.
For Self-Employed Borrowers
You’ll need a letter from a CPA, bookkeeper, or tax preparer validating that you work full-time. A Letter of Explanation from the borrower alone attesting to full-time status is not acceptable—this documentation must come from a third party.
Why This Program Matters for Palm Beach County Buyers
Palm Beach County’s housing costs have climbed significantly in recent years, and for the teachers, nurses, and first responders who keep our communities running, saving enough for a down payment can feel out of reach even with a stable income.
I’ve worked with several local frontline workers who assumed homeownership in Palm Beach County simply wasn’t realistic on their salary. When we ran the numbers using Hometown Heroes assistance, the picture changed considerably.
A nurse working full-time at a Florida-based hospital, for example, could receive $15,000-$25,000 toward her down payment and closing costs on a typical Palm Beach County starter home, plus save on the standard 1% origination fee.
This program essentially removes one of the biggest barriers to homeownership for exactly the workers our communities depend on most.
Frequently Asked Questions
Do I need to work in a specific job title to qualify for Hometown Heroes?
No. Eligibility comes down to who employs you and where you physically work, not your job title. A cafeteria worker or janitor at a hospital or K-12 school qualifies, while a fully remote employee in any occupation does not.
Can remote workers qualify for this program?
No. Remote and work-from-home employees are not eligible. Hybrid employees can qualify, but only if they’re on-site at least three days per week at a Florida-based physical location.
Is the Hometown Heroes assistance a grant I never have to repay?
No. It’s a 0% interest, non-amortizing, 30-year second mortgage. There are no monthly payments, but the full amount must be repaid when you sell, transfer the deed, pay off your first mortgage, refinance, or stop occupying the home as your primary residence.
What’s the minimum and maximum assistance I can receive?
You’ll receive 5% of your total loan amount, with a minimum of $10,000 and a maximum cap of $35,000. Loans of $200,000 or less automatically receive the $10,000 minimum.
What credit score do I need?
You need a minimum FICO score of 640 for all loan types. Manufactured housing and manual underwrites require a minimum of 660.
What’s the difference between the TBA and Bond versions?
TBA only counts income from borrowers actually on the loan and offers FHA, USDA-RD, VA, and Freddie Mac HFA Advantage loans. Bond counts income from everyone in the household aged 18 and older, including a non-borrowing spouse, and is the only path to a Fannie Mae HFA Preferred conventional loan for 2026.
Can I use this program if I’ve owned a home before?
Generally, no. You must not have had an ownership interest in your primary residence within the last three years, unless you’re purchasing in a Federally Designated Targeted Area or qualifying under the Veteran’s Exemption.
Do veterans have to work in an approved occupation to qualify?
No. Veterans with a valid DD-214 don’t need an eligible-type employer, but they must still be employed full-time by a Florida-based employer to qualify.
Can I combine Hometown Heroes with another Florida Housing down payment program?
No. Florida Housing’s down payment assistance programs cannot be stacked, and all borrowers are limited to one-time participation across all of Florida Housing’s first and second mortgage programs.
Can I refinance my current home using this program?
No. This program is for home purchases only. Refinances are not eligible under Hometown Heroes.
Is there a homebuyer education requirement?
Yes, the primary borrower must complete an approved pre-purchase homebuyer education course, in-person or online. Certificates are valid for two years. Veterans and active-duty military are exempt unless using a conventional HFA Preferred or HFA Advantage loan.
Ready to See If You Qualify?
Between the down payment and closing cost assistance, the waived origination fee, and a competitive fixed rate, the Hometown Heroes Program can make a meaningful difference for Florida’s frontline workers looking to buy their first home in Palm Beach County.
Because eligibility depends heavily on documentation of your employer and work location, and because choosing between TBA and Bond can significantly affect your qualifying income, working with someone familiar with the program’s details helps avoid costly missteps.
If you work in healthcare, education, law enforcement, first response, childcare, the courts, or you’re a veteran or active military member, I’d be glad to help you figure out whether you qualify and what homes in Palm Beach County fit your budget once this assistance is factored in.
Reach out today to start the conversation—verifying your eligibility costs nothing, and it could be the difference between renting another year and owning your first home.
Contact:
Ernst Cenege – Realtor
Phone: 561-618-9984